
Key takeaways from the 2026 Banking Transformation Summit and what financial institutions need to consider as they navigate the next era of innovation.
The banking industry is at an interesting inflection point. Technology is advancing at a pace that is difficult for even the most innovative organizations to keep up with, and financial institutions are facing increasing pressure to modernize, embrace artificial intelligence, and rethink how they deliver products and services to customers.
For an industry that has traditionally taken a more measured approach to technology adoption, the pace of change represents both an opportunity and a challenge.
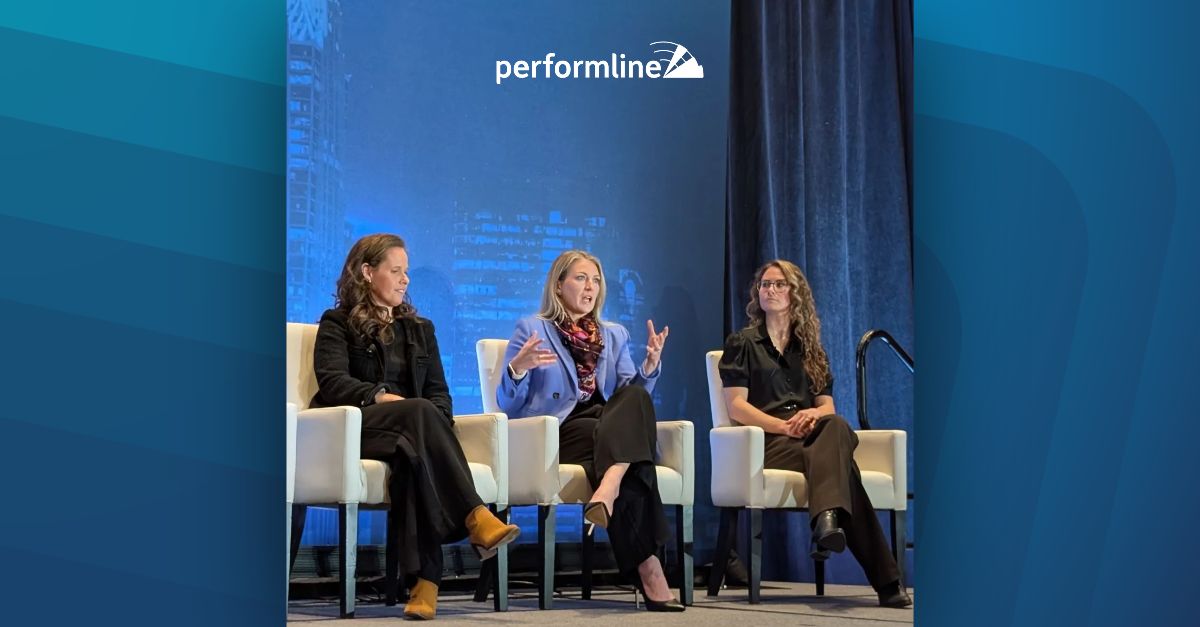
That was a recurring theme throughout this year’s Banking Transformation Summit in Charlotte, where banking leaders, technology providers, fintechs, and industry experts came together to discuss the future of financial services.
Across conversations about AI, customer experience, digital assets, tokenization, and banking infrastructure, one message stood out: The future of banking will be shaped not just by how quickly institutions adopt new technology, but by how thoughtfully they put it to work.
The Pressure to Innovate Is Only Increasing
Traditional financial institutions are operating in an increasingly competitive environment. Fintech companies have raised customer expectations around convenience, speed, personalization, and digital experiences. Customers are no longer comparing their banking experience exclusively to other banks. They’re comparing it to the seamless digital experiences they encounter across every aspect of their lives.
This puts pressure on banks and credit unions to evolve.
AI, automation, and emerging fintechs offer significant opportunities to improve operational efficiency, personalize customer interactions, streamline processes, and introduce new products and services.
But the ability to adopt these technologies isn’t equal across the industry.
Larger financial institutions may have dedicated innovation teams, technology budgets, and infrastructure to explore and implement emerging capabilities. Community banks and credit unions often face a different set of considerations. They must find ways to remain competitive while navigating resource constraints, legacy systems, evolving regulatory expectations, and the challenge of determining where to invest.
For many smaller institutions, the question isn’t simply whether they should embrace AI or modernize their technology. It’s how to build the infrastructure, capabilities, and internal expertise to do so responsibly.
The competitive pressure is real, and standing still isn’t a viable option.
Innovation Shouldn’t Come at the Expense of Trust
While much of the summit focused on what’s next for banking, an important part of the conversation centered on what shouldn’t change.
Regardless of whether an institution is offering traditional banking products, exploring tokenized assets, or introducing AI-powered services, the fundamentals of financial services remain the same: trust, transparency, reputation, and protecting the customer.
I had the opportunity to participate in two panel discussions that explored these themes from different perspectives.
During Customer Journeys That Earn Loyalty, Not Just Logins, we discussed how financial institutions can create experiences that build lasting customer relationships. Technology should make banking easier, more accessible, and more responsive to customer needs, but it shouldn’t replace the human connection or become the objective in itself.
During Designing the Future of Capital with Tokenization: Risk and Infrastructure, our conversation explored how emerging technologies and digital assets are reshaping financial markets and infrastructure. As institutions bridge traditional finance with new digital capabilities, they must also consider the risks, responsibilities, and customer expectations that come with that evolution.
Both discussions reinforced a similar point: Innovation and customer trust cannot be treated as separate priorities.
A new product, digital experience, or AI-powered capability is only valuable if customers understand it, trust it, and can confidently engage with it. Financial institutions must be equally thoughtful about how new offerings are introduced, how they’re marketed, and how their brands are represented throughout the customer journey.
AI Is Changing the Marketing Landscape, Too
One of the most significant implications of AI adoption is its impact on how financial institutions communicate with customers.
Generative AI is making it easier than ever to produce marketing content, personalize messaging, and engage customers across multiple channels. Marketing teams can create more campaigns, more variations, and more customer touchpoints in less time.
That creates tremendous opportunities for growth.
It also introduces a challenge: How do compliance and risk management teams keep pace?
Traditional marketing compliance processes were often designed around a more predictable volume of content, established publishing workflows, and manual review. But when AI accelerates content production, those same processes can quickly become bottlenecks.
Consider the possibilities:
- Marketing teams using AI to generate website copy, email campaigns, social media posts, and product descriptions.
- Financial institutions using automation to personalize communications and customer interactions at scale.
- Third-party partners, affiliates, and other distribution channels creating content that references a financial institution’s products and services.
- Consumers increasingly using AI platforms to research financial products and receive information about banks and other financial institutions.
Each of these developments creates additional considerations for compliance, brand oversight, and consumer protection.
The underlying obligations don’t disappear because AI was involved in creating the content. Financial institutions remain responsible for ensuring that their marketing and customer communications are accurate, transparent, and aligned with applicable requirements.
The challenge is making sure oversight evolves at the same pace as innovation.
PerformLine Data:
8%
of assets reviewed contained potential issues. That sounds small—until you zoom out to the hundreds of thousands of URLs many enterprises have in the wild. At that scale, 8% is no longer a rounding error; it’s meaningful exposure.
AI Isn’t Replacing People. It’s Changing How We Work.
One of the most interesting themes I heard throughout the summit was the role of humans in an increasingly AI-driven banking environment.
There’s a lot of conversation right now about artificial intelligence, superintelligence, and what these technologies might eventually mean for the workforce. But across several sessions, I heard a consistent perspective: AI isn’t meant to replace the people responsible for making financial institutions operate safely and effectively. It’s meant to help them do their jobs better.
In banking especially, having knowledgeable, capable people involved in decision-making, risk management, and customer protection isn’t optional. It’s essential.
AI can help teams process information faster, analyze massive amounts of data, identify patterns, and take on repetitive or time-consuming tasks. That creates more opportunities for employees to focus on higher-value work that requires experience, critical thinking, and sound judgment.
But there’s an important caveat: AI is only as effective as the information it’s given.
There’s a familiar phrase in technology: “garbage in, garbage out.” If the data feeding an AI model is inaccurate, incomplete, outdated, or poorly managed, the output is going to reflect those shortcomings. In fact, AI doesn’t necessarily solve a bad data problem. It can simply help you produce bad information faster and at a much greater scale.
That’s a particularly important consideration for financial institutions, where inaccurate information or poorly governed processes can have real consequences for customers, compliance, and institutional reputation.
The opportunity isn’t to remove humans from the equation. It’s to combine the speed and analytical capabilities of AI with the experience, judgment, and accountability of the people overseeing it.
Ultimately, the strongest AI strategies won’t just focus on what can be automated. They’ll focus on where technology can empower people to make better, more informed decisions.
Compliance Needs to Scale Alongside the Business
Historically, compliance has sometimes been viewed as a checkpoint at the end of the marketing or product development process. But that approach becomes increasingly difficult to sustain as financial institutions expand their digital presence and accelerate content production.
The opportunity is to make compliance more proactive and integrated into the way institutions operate.
This means having visibility into where a brand and its products are being represented, establishing consistent standards across channels, identifying potential issues earlier, and equipping compliance teams with the tools to manage increasing volumes of content and activity.
Technology can play an important role in making this possible.
At PerformLine, we believe financial institutions shouldn’t have to choose between growth and responsible oversight. Our approach is centered on helping organizations scale their marketing compliance programs through technology, automation, and AI-powered monitoring, while maintaining the human oversight and accountability that regulated industries require.
Whether it’s identifying potential compliance issues across digital channels, monitoring third-party marketing activity, or reviewing content before it reaches consumers, the goal is to help institutions gain greater visibility and control without relying entirely on manual processes.
As AI continues to change how financial services organizations operate and communicate, these capabilities will become increasingly important.
The Next Era of Banking Requires Both Innovation and Accountability
The conversations at the Banking Transformation Summit made one thing clear: The banking industry is not slowing down.
AI, automation, digital assets, and new financial infrastructure will continue to reshape how institutions compete, operate, and serve their customers. The organizations that navigate this transition successfully will need to be willing to challenge traditional approaches, invest in new capabilities, and rethink how they deliver value.
But innovation alone isn’t the measure of success.
Financial institutions must continue to protect the trust they’ve built with customers and members, maintain the integrity of their brands, and ensure that the products, services, and experiences they introduce are supported by appropriate risk management and compliance practices.
The future of banking isn’t just about adopting what’s next. It’s about making sure that as the industry evolves, the fundamentals that make financial services work don’t get left behind.
See how PerformLine can help
 Rhonda McGill